Introduction
Borrowing in the UAE looks different this year than it did even twelve months ago. The Central Bank has held its base rate steady at 3.65 percent through much of 2026, giving borrowers a period of relative predictability, while total UAE banking sector assets have grown past Dh5.42 trillion. At the same time, residents are being noticeably more selective about new borrowing, and younger consumers are increasingly turning to buy-now-pay-later schemes instead of traditional credit. Understanding how these shifts affect everyday debt management decisions helps UAE residents plan more effectively, whether they are managing existing debt or deciding whether to take on new obligations. Global Debt Rescheduling Services tracks these trends closely because they directly shape the advice given to clients working through debt management plans today.
Why Steady Interest Rates Are Only Part of the Picture
A steady base rate means monthly instalments on variable-rate loans are not climbing further for now, which is genuinely good news for residents already repaying debt. But steady rates do not undo the effect of several years of rising living costs, and they do not reduce a balance that is already outstanding. Effective debt management in this environment means using the current stability to make real progress on existing balances, rather than assuming the pressure has fully eased.
The Shift Toward Selective, Affordability-Focused Borrowing
Recent lending data shows UAE residents borrowing with more caution than in previous years — credit is still expanding, but demand is shifting away from discretionary spending and marginal borrowers toward cards, personal loans, and property-backed lending from applicants who can clearly demonstrate affordability. This shift matters for debt management because banks are applying the same caution when reviewing restructuring or consolidation requests, which means a well-documented, realistic proposal carries more weight than ever.
Buy-Now-Pay-Later and the New Face of Consumer Debt
One of the more notable developments this year is the growing popularity of buy-now-pay-later schemes among younger UAE consumers, often used as an alternative to traditional personal loans or credit cards. While these schemes can feel less like “real debt” because repayments are small and spread out, missed instalments still affect a resident’s financial standing and can stack up alongside other obligations just as quickly as a credit card balance. Debt management strategies increasingly need to account for this category of spending, not just conventional bank debt.
What This Shift Means for Business Debt as Well
Businesses are navigating a similar recalibration. Banks reviewing corporate facilities are placing more weight on demonstrated cash flow and less on projected growth alone, which mirrors the affordability-first approach now applied to personal lending. Business owners managing existing facilities are finding that a well-documented restructuring proposal, built around actual trading figures rather than optimistic forecasts, is far more likely to succeed in the current environment than it might have been two or three years ago when credit conditions were looser across the board.
What This Means for Anyone Currently Managing Debt
- A stable rate environment is a good window to negotiate restructuring terms, since banks have more predictability too
- Property-backed and salary-transfer debt is being treated more favourably by banks than unsecured, discretionary borrowing
- Buy-now-pay-later balances should be included in any full picture of monthly obligations, even though they rarely appear on a traditional credit report review
- Banks are scrutinizing affordability more closely, so a debt management proposal needs clear supporting documentation to succeed
Relatable post – How to Choose the Best Debt Management Companies in Dubai?
How Global Debt Rescheduling Services Applies These Trends to Client Strategy
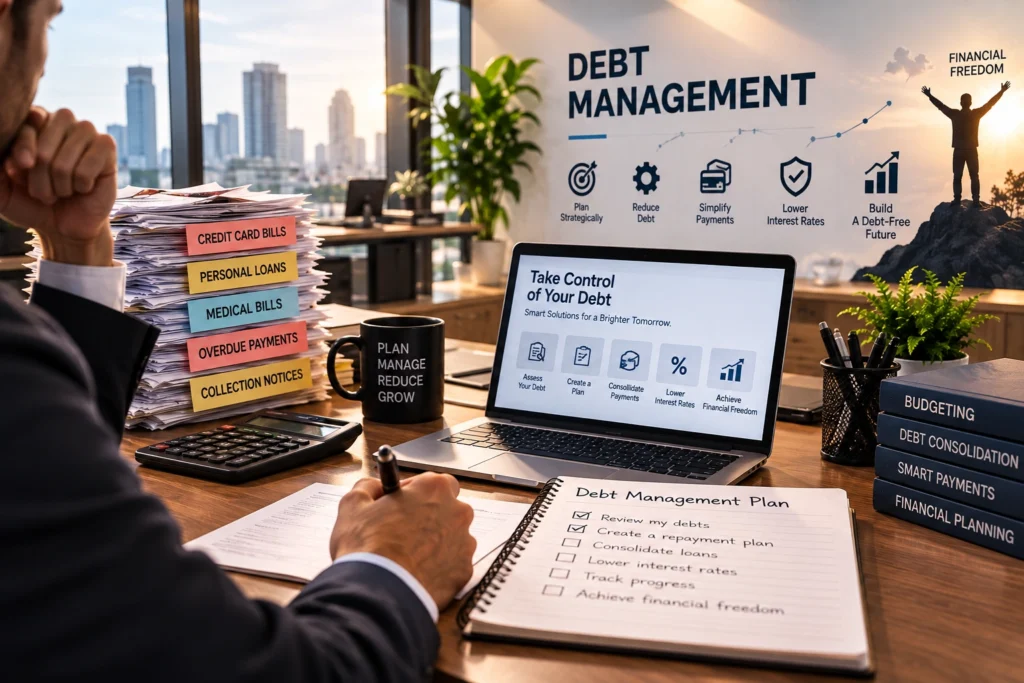
Global Debt Rescheduling Services builds debt management plans around the current lending environment, not a generic template. That means factoring in where banks are currently showing flexibility, being realistic about where they are not, and accounting for the full range of obligations a client carries — including newer forms of consumer credit that older debt management approaches often overlook. Two clients with an identical total balance today may need very different strategies depending on whether their debt sits in traditional bank facilities or is spread across several smaller instalment schemes, and treating those two profiles the same way rarely produces the best outcome for either.
Conclusion
Debt management in the UAE is being shaped by a steadier interest rate environment, more cautious bank lending, and new forms of consumer credit that did not exist a few years ago. Understanding these trends helps residents make better decisions about existing debt and any new borrowing they are considering. Global Debt Rescheduling Services builds every debt management strategy around the current UAE lending landscape, not outdated assumptions. Contact Global Debt Rescheduling Services today to review your debt management options in light of where the market actually stands.